Skip to main content

Monetary Policy

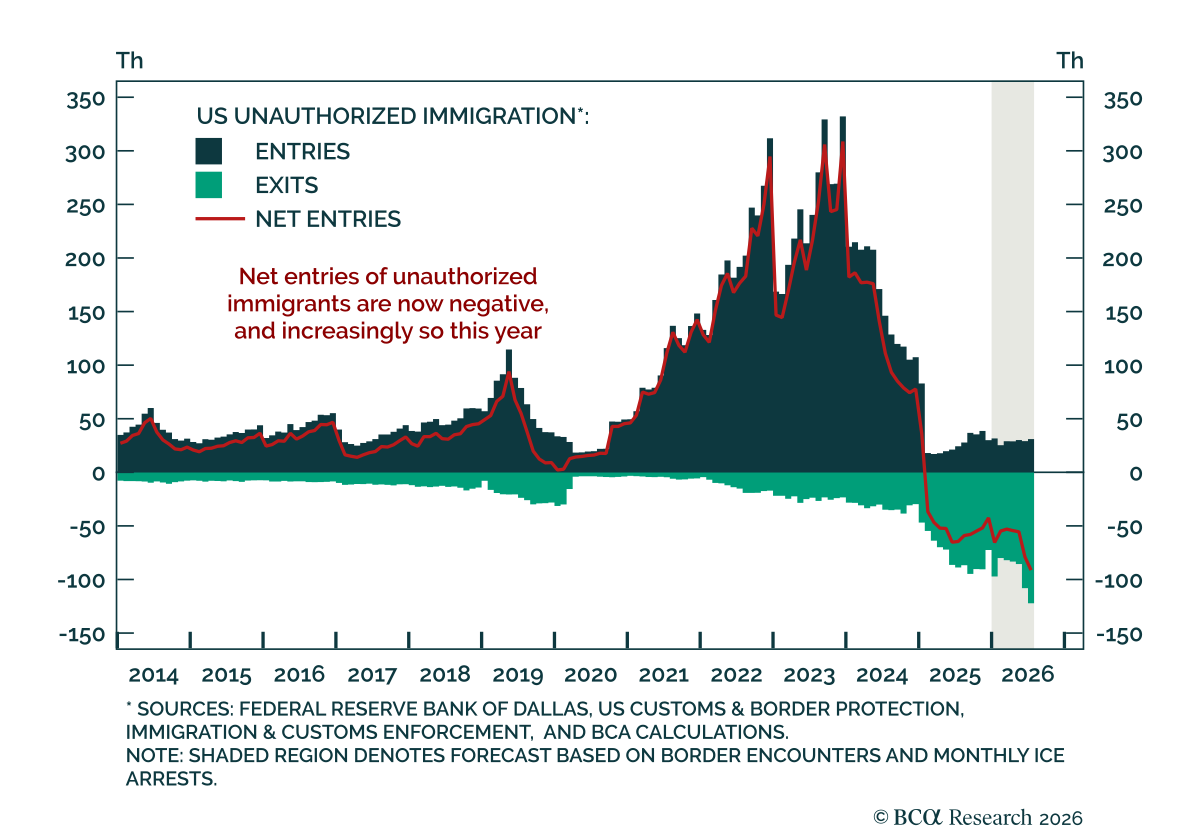
Our Essentials and CoreMacro strategists find little evidence that tighter labor supply from the US immigration crackdown is boosting inflation today. The net exit of unauthorized immigrants has nonetheless lowered the bar for stronger labor demand to turn…

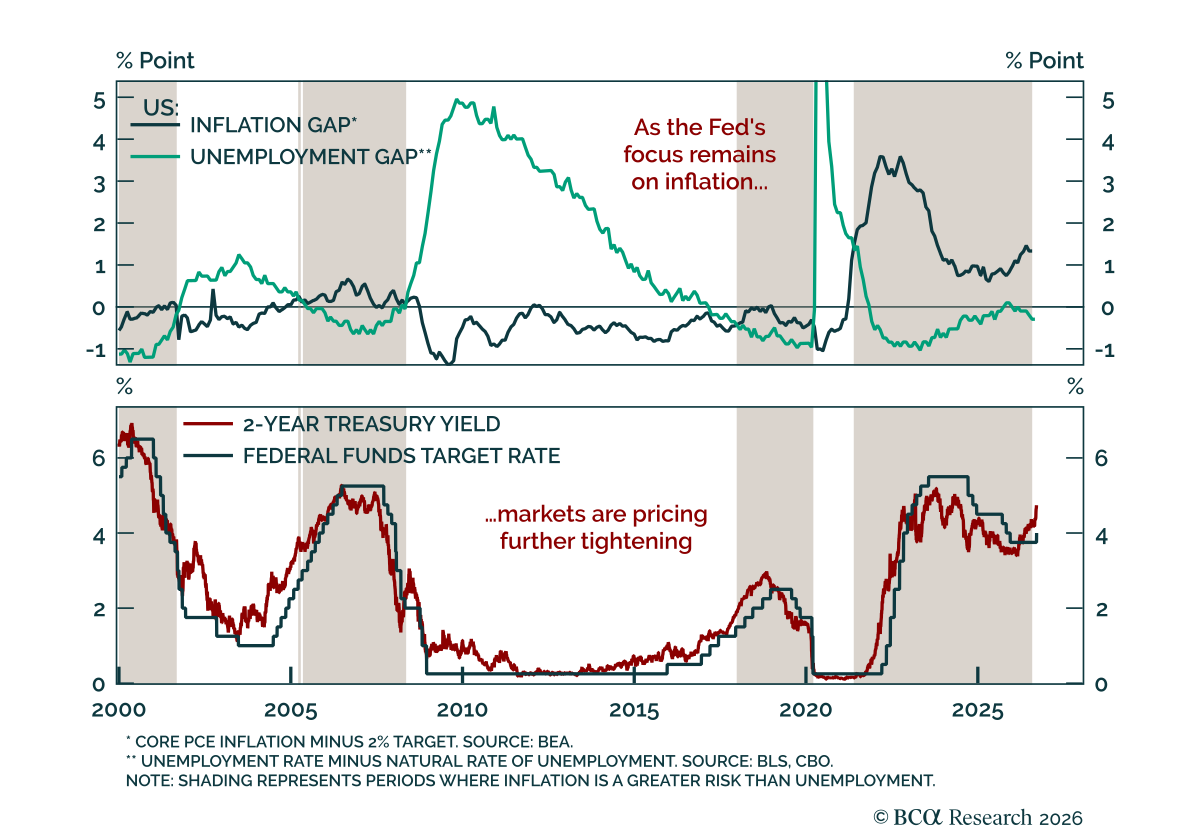
The Fed hiked rates last week, but Fed officials expect this tightening cycle will involve no more than three 25-basis point hikes, contingent on inflation coming down quickly in 2027. We’re inclined to agree.
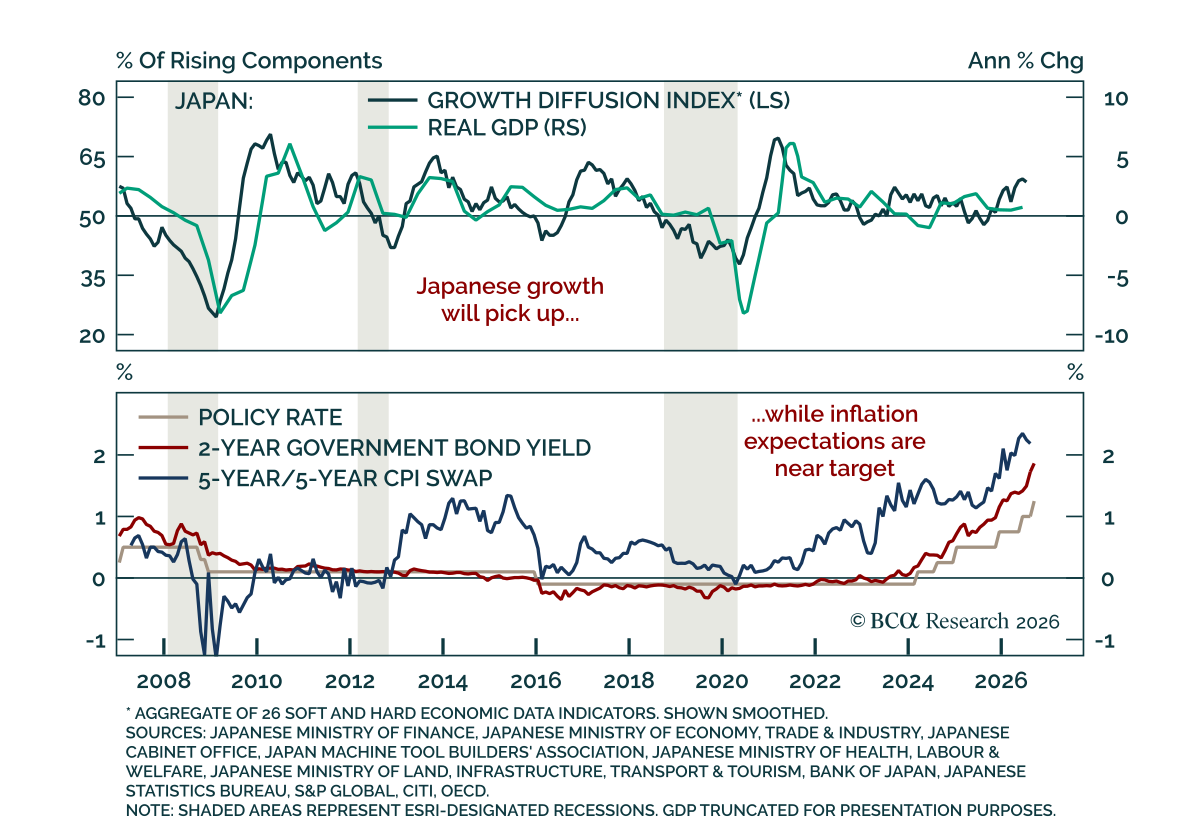
The BoJ hiked rates by 25 bps to 1.25%, but less-hawkish guidance and cooler inflation data created a dovish repricing. The move, which took the policy rate to its highest level in 31 years, was in line with expectations. However, the split vote, with…

Labor supply is not meaningfully boosting inflation today, but the net exit of unauthorized immigrants has lowered the bar for stronger labor demand to turn inflationary. Hawkish monetary policy surprises over the coming year are possible.
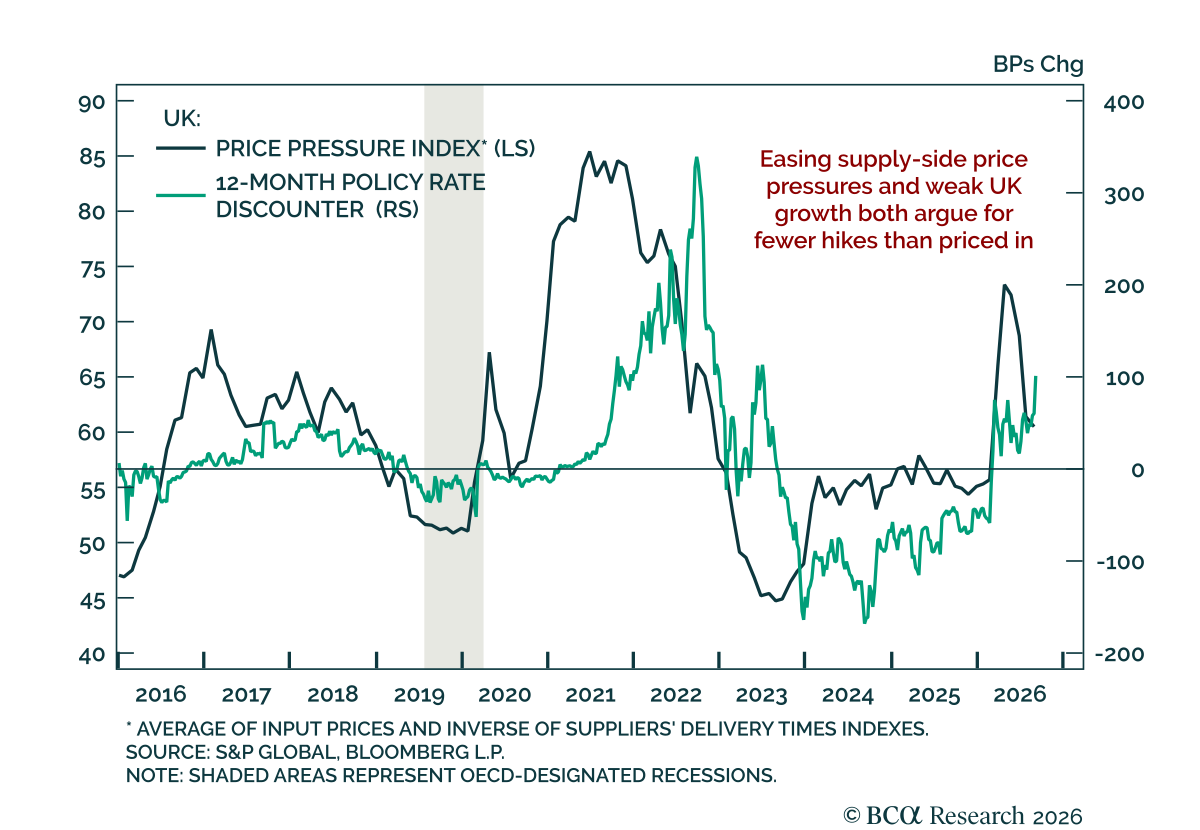
The BoE held rates at 3.75%, but despite a more cautious tone on inflation, the UK economy still shows little risk of overheating or second-round effects, supporting our overweight on gilts. The decision was split 6-3, with Greene, Mann, and Pill voting for a…
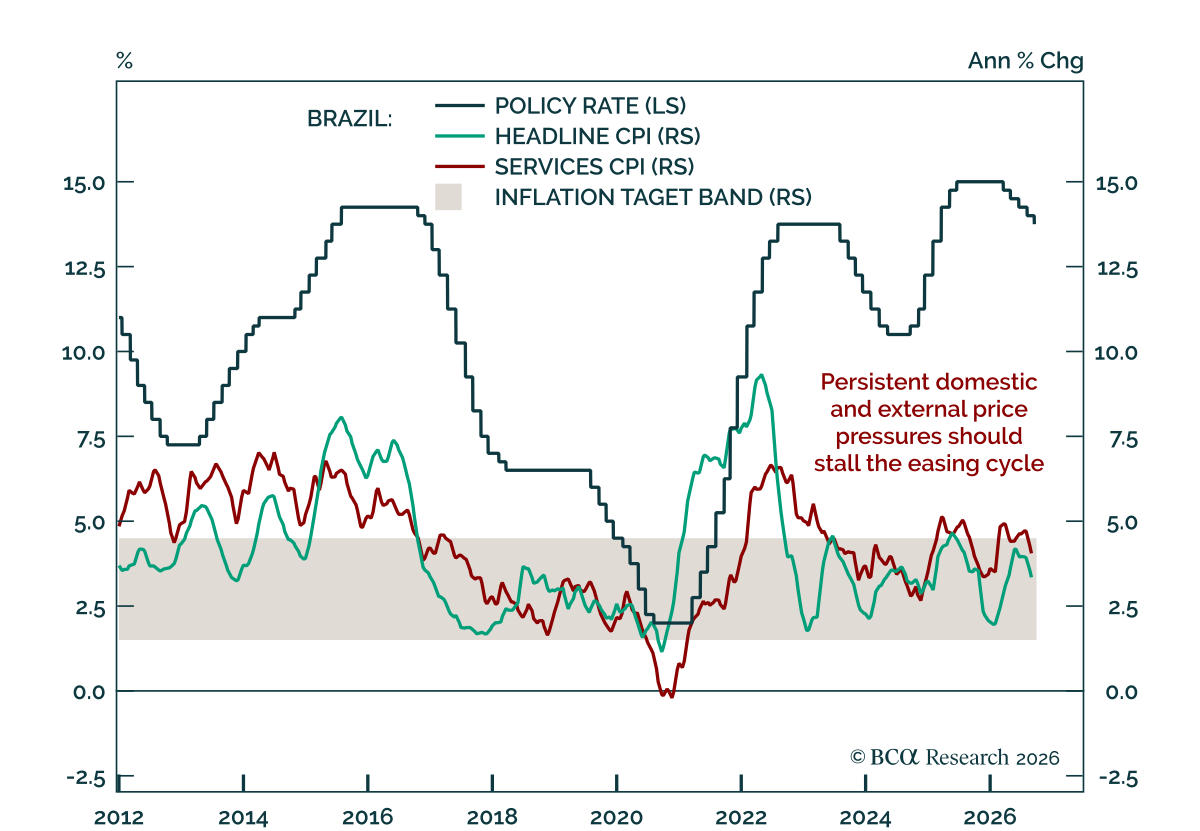
Brazilian inflation has eased enough for the BCB to continue cutting rates, but persistent domestic and external pressures should bring the easing cycle to a pause. The central bank delivered a fifth consecutive 25 bps cut, taking the policy rate to 13.75%.…
The Fed’s 25 bps hike confirms the start of a new tightening cycle, but our US Bond strategists still expect that cycle to be mild and front-loaded. The FOMC unanimously lifted the fed funds target range to 3.75%-4%, with the statement saying the move was…

The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.


Scott Bessent’s attempts to suppress yields while financing large twin deficits risk crashing foreign inflows, the dollar, US bonds, and equities. Without a major equity selloff or large-scale commercial bank purchases of Treasurys, the bond selloff will persist – producing a major equity drawdown and a lower dollar.

The August CPI report was slightly hotter than expected and guarantees a Fed hike on Wednesday; but there is still no evidence of broadening inflation pressures or second-round effects. Headline CPI was in line with consensus at 0.4% m/m, leaving the annual…