Indonesia

Indonesia’s policy easing will boost domestic demand, but fuel inflation. Current account deficit will widen, and the rupiah will weaken. Stay short the rupiah and go underweight Indonesian stocks, domestic bonds, and sovereign credit in their respective EM portfolios.


In this chartbook, we look at the balance of payments across DM and EM countries. The US does not fare well, but neither do a few other countries.
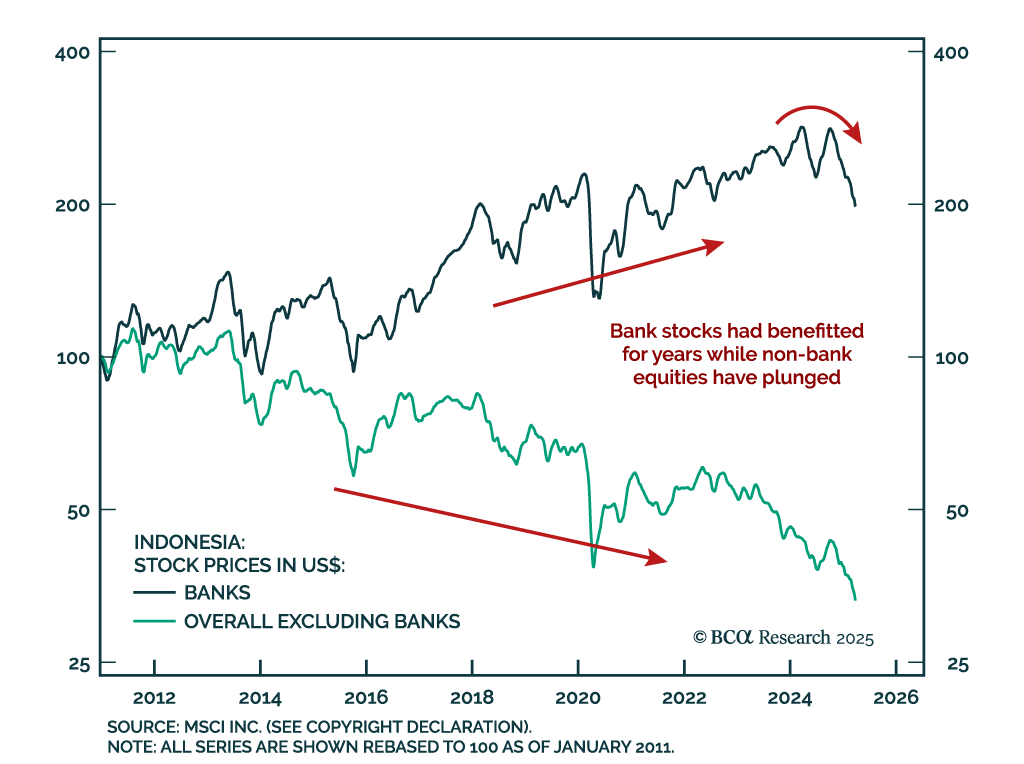

There is an ongoing regime shift in Indonesia: SOEs will be used to drive economic growth. Bank loans will accelerate, but their profit margins will shrink. Despite higher nominal growth, Indonesian equity prices in US dollar terms will not see a sustainable bull market. Downside risks to currency and upside risks to domestic bond yields have also increased.

The ongoing rally in ASEAN currencies will fizzle sooner rather than later as they are not supported by fundamentals. The ringgit and the baht, however, will fare better than the peso and the rupiah during the coming global risk-off period. This report explains why.

A major slowdown in nominal growth was behind Indonesia’s recent stock underperformance. Dedicated EM equity portfolios should upgrade Indonesian stocks from underweight to neutral. We also recommend a new relative trade: go long Indonesian banks / short EM banks.

ASEAN stocks and currencies will weaken further as these economies face multiple headwinds. Raising policy rates did not stop a sliding currency in the past, it is unlikely to do so now.