Developed Countries

US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.

The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.

US inflation came in hot for the second consecutive month in September, though probably not hot enough for the Fed to move its next rate hike up to the October meeting.
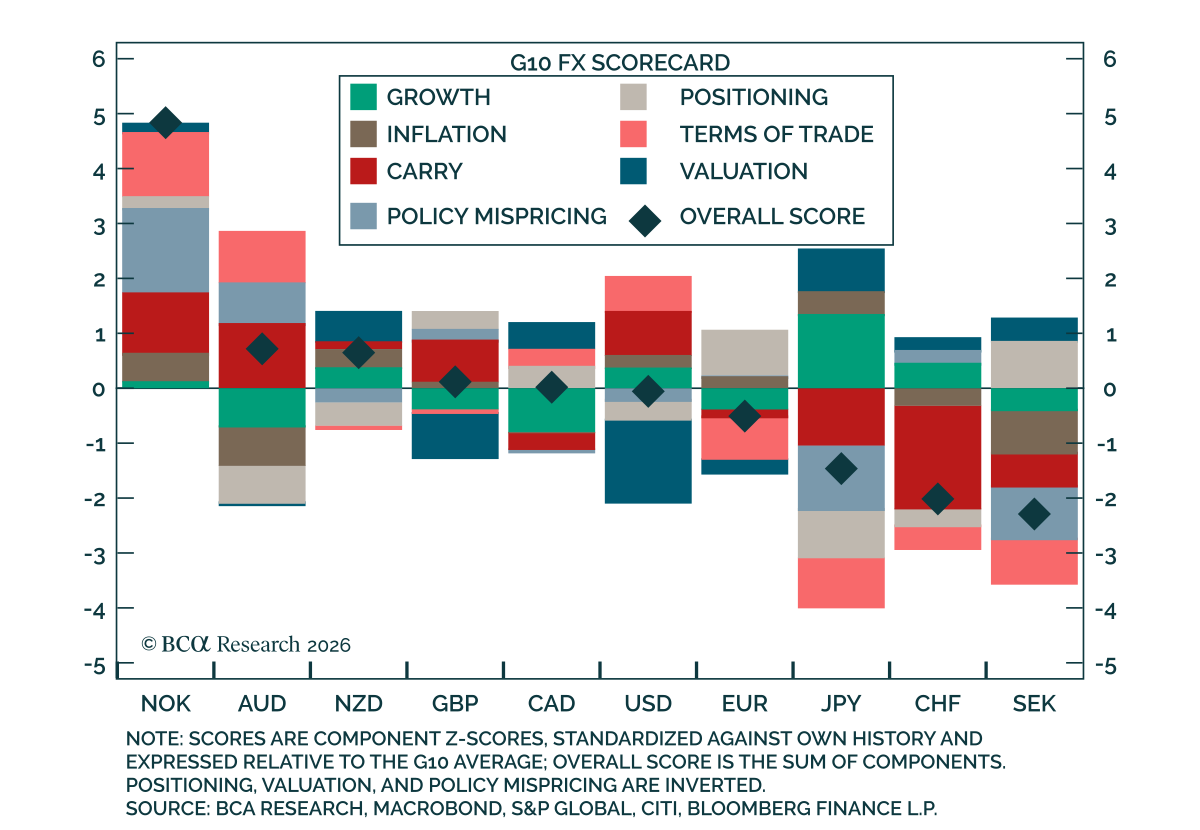


Our G10 FX cyclical scorecard still favors high-carry currencies over low yielders, suggesting patience should continue to pay. We break down the factors driving each currency and highlight the most appealing relative-value opportunities.

This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.

Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.

US corporate balance sheet health looks strong overall, and credit metrics aren’t showing any significant negative impact from the AI issuance boom.

The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.