AI

The IPO wave has arrived, dominated by SpaceX’s massive listing. Aftermarket performance has been weak, and elevated issuance is weighing on S&P 500 multiples, although some pressure is already priced. SpaceX remains only partly digested, while Anthropic and OpenAI will bring further supply and greater business model scrutiny.


Concerns by the major AI companies that they are locked into a financially unsustainable arms race for AI dominance are likely playing as much a role in their newfound “go slow” approach as concerns over AI doom.

An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.

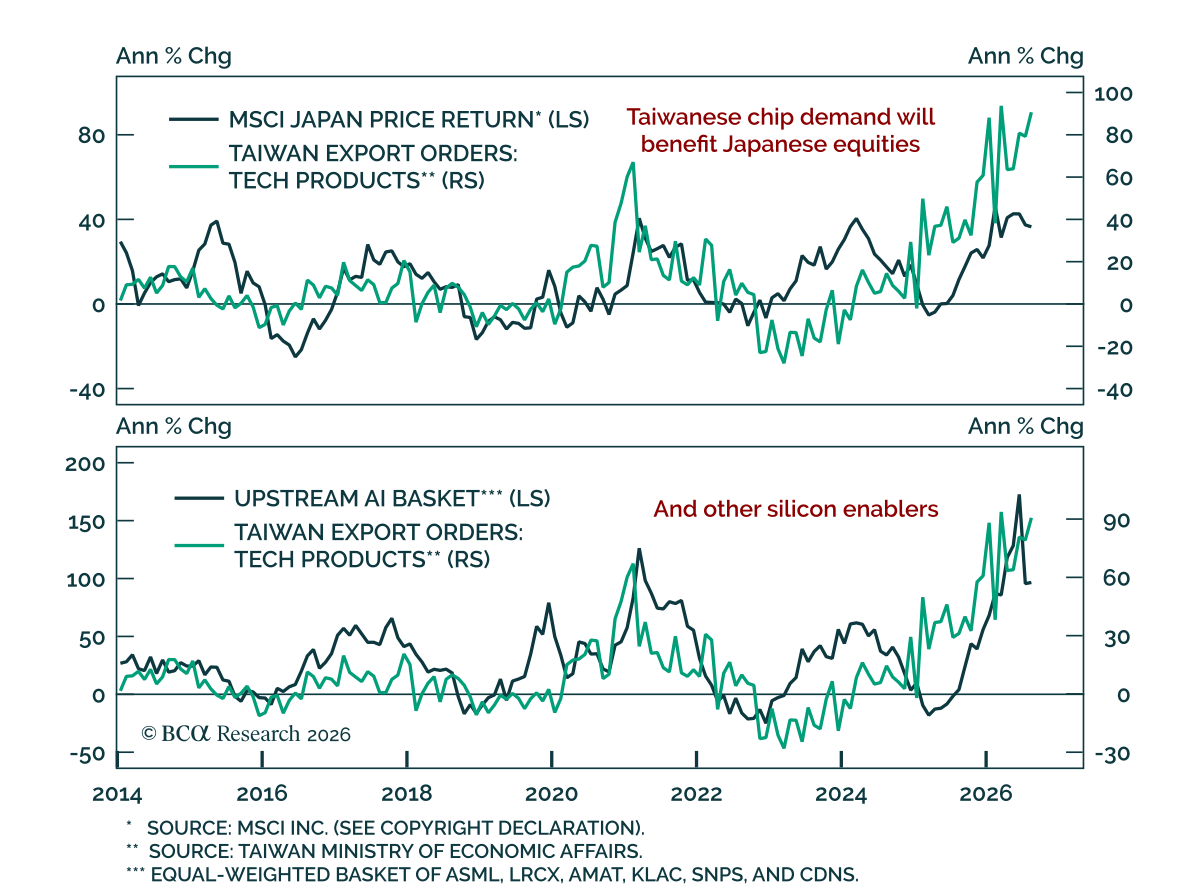
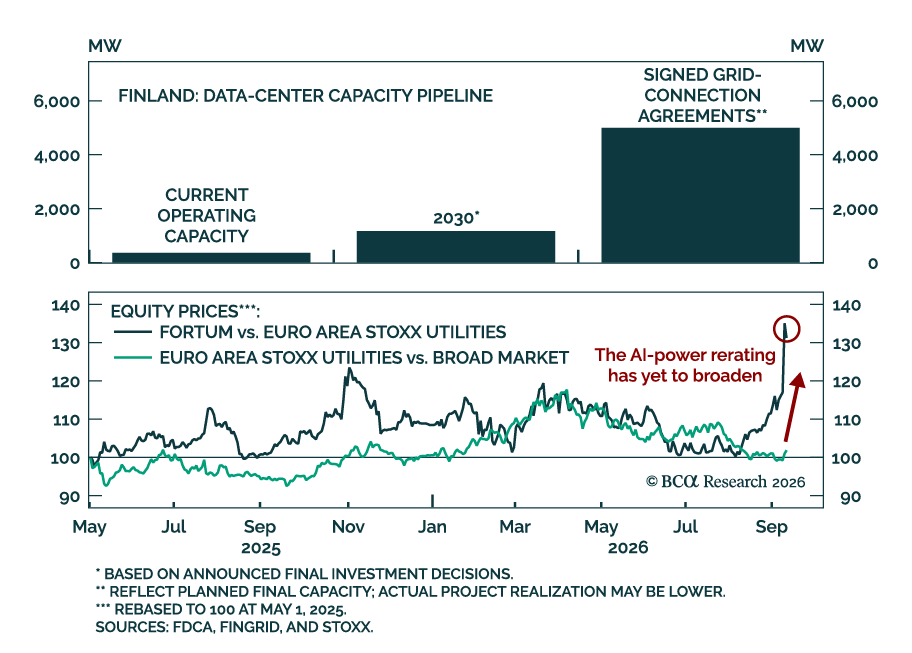
In this report, we explore opportunities in goldminer equities, AI infrastructure monetization, and Japan's tactical outperformance window.

We remain tactically bullish due to the combination of geopolitical risks in the Middle East easing and the ramping up of the AI boom. In this month’s chartpack, we articulate the reasoning behind both sanguine views.

AI demand remains strong, but the capex boom is creating a growing divide within Tech. Hyperscalers combine superior margins, capital efficiency and financing capacity with multiple paths to monetize AI investment. Neoclouds rely more heavily on leverage and scarcity economics, potentially making them more vulnerable should capacity expand and compute pricing normalize.
