Latest from BCA Research


Last week, I visited clients in Europe. My recent report on Bessenomics – the name we gave to US Treasury Secretary Scott Bessent's policy mix – was often the focal point of the discussions. We will continue discussing Bessenomics, its progress, and its investment implications in forthcoming reports. In the meantime, we are sending my chart pack used during this trip as a Charts That Matter publication – a chart-based report. It covers the following areas: China, Bessenomics, US fixed income, global currencies, EM credit markets, the global ex-US business cycle, EM and US equities, and an EM local bond relative value matrix. In my opinion, the most important variable in global financial markets are US long-term Treasury yields. If they hold above their 200-day moving average, odds are that new highs lie ahead. My hunch is that 10-year yields will break above 5%. When and as this happens, global risk assets will sell off considerably.

We were stopped out of our defensive asset allocation recommendations last Thursday, when the S&P 500 closed above 6,100, but our reading of the labor market tea leaves still supports a bearish fundamental view.

Global risk assets are engulfed in a wave of euphoria, which is pulling Europe higher along the way. However, risks still abound. How should investors adjust their allocation to Europe under these highly uncertain conditions?
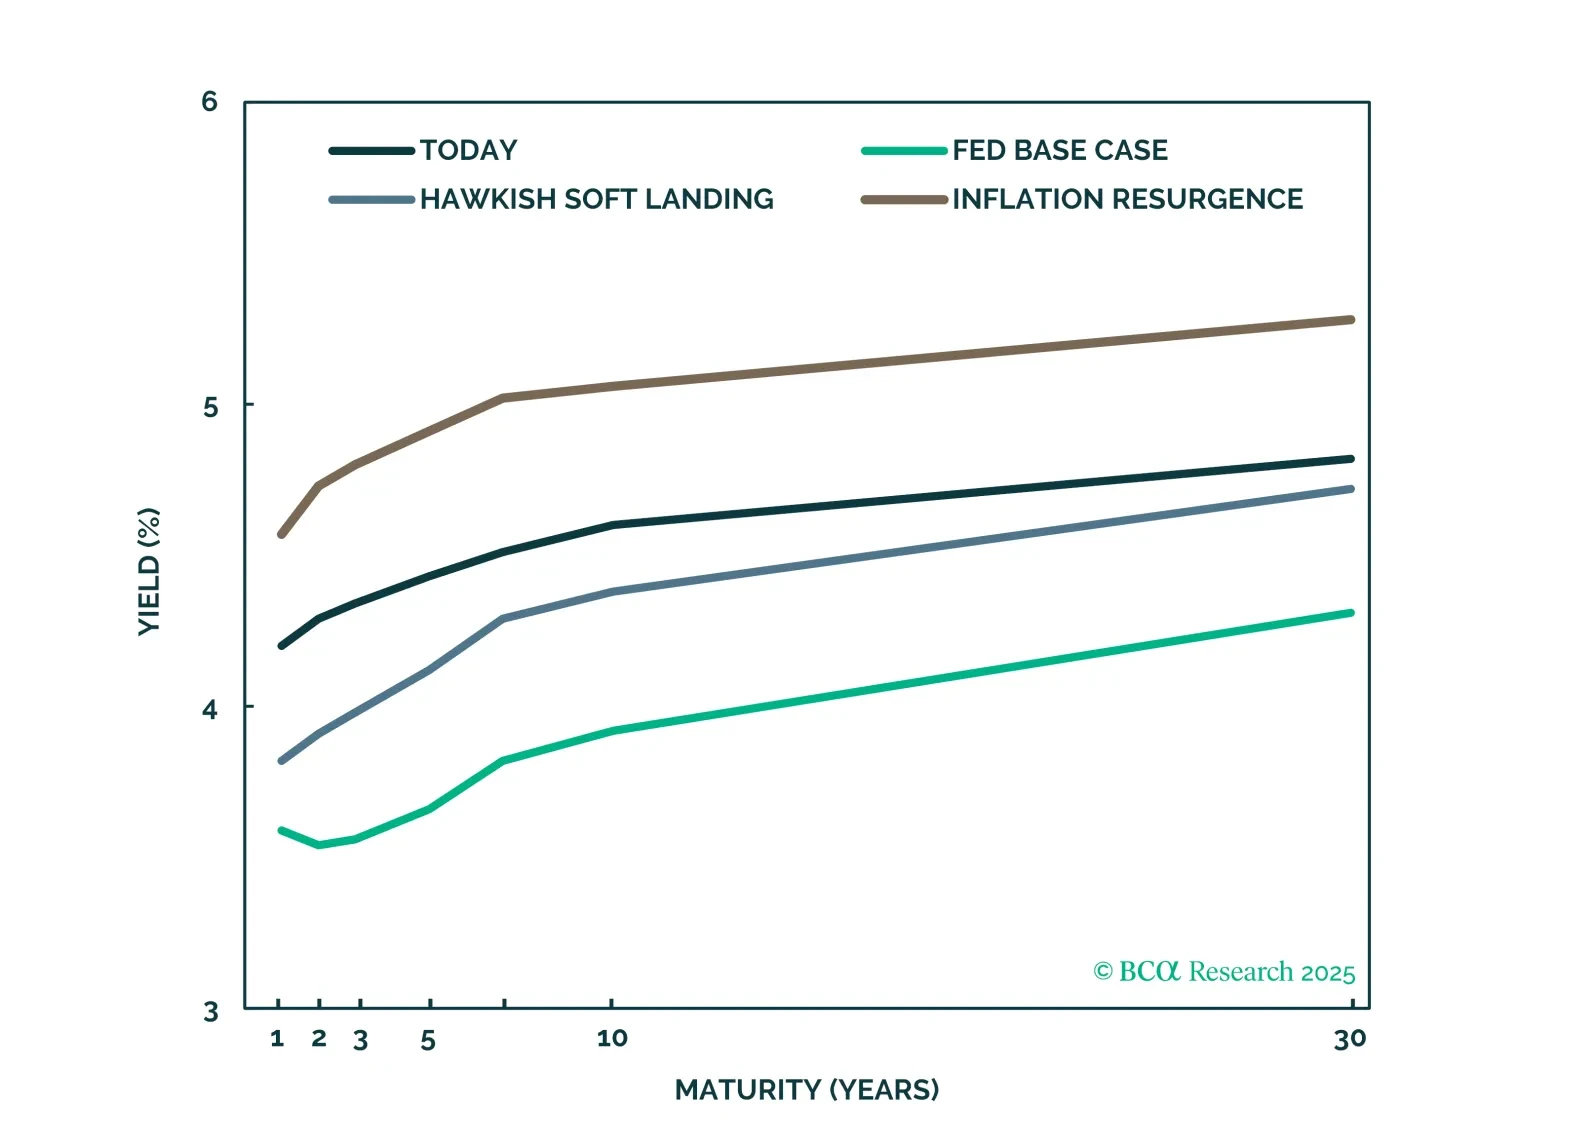
We forecast Treasury and corporate bond returns in three different economic scenarios. This report focuses on what returns might look like in a scenario where inflation is sticky and the Fed makes a hawkish pivot.

This week, our three screeners show you how to setup easy monitoring of the BCA Score, take advantage of earnings season in the US, and seek out global stocks that are cheap and high quality.

In today’s Strategy Insight, we discuss the monetary policy outlook for the Bank of Japan, following the 25-bps rate hike overnight, and what it means for JGBs and the yen.

While the US economy could remain upright on the tightrope for a while longer, it will inevitably fall, leading to a major bear market in stocks. We will be looking to our MacroQuant model for guidance on when to turn fully defensive. We are not there yet.

Sentiment will stay positive for now, but downside risks are rising. Investors should proceed cautiously in stock picking and portfolio construction at this juncture, given rising economic and policy uncertainty, which threaten market sentiment, and more broadly, the current bull-market.
