Japan


MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.

We review our Model Bond Portfolio performance for Q3 and look ahead as energy prices continue to drive fixed income markets. Balanced labor markets point to a mild tightening cycle, creating opportunities in government bonds and credit, while inflation-linked bonds continue offering protection against persistent energy risks.

MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
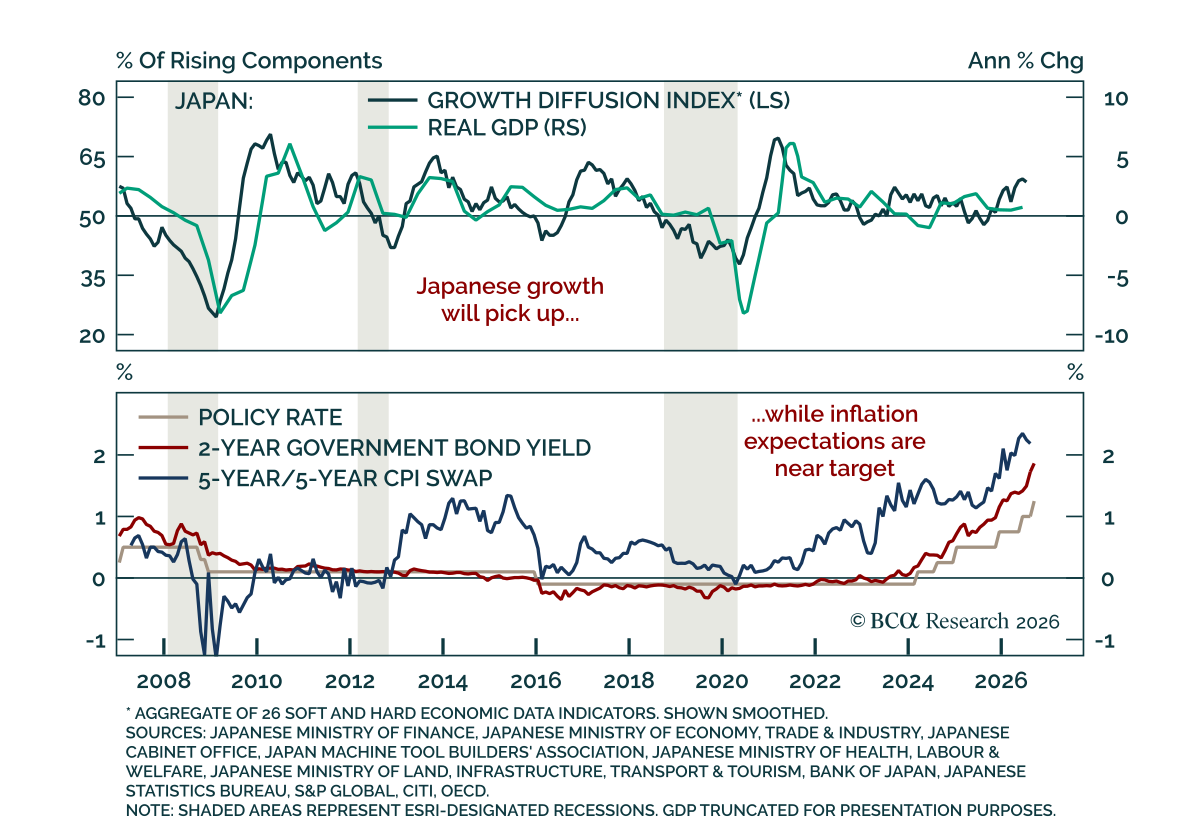

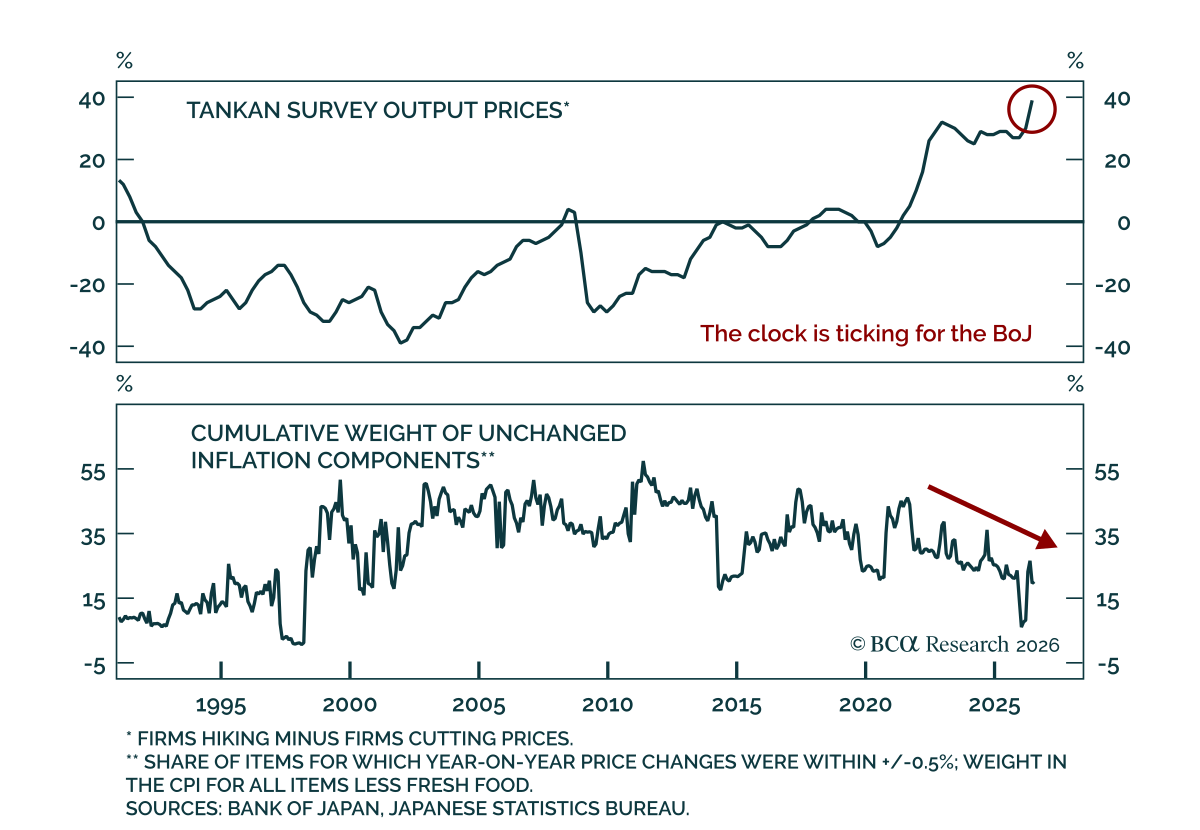

The yen's next leg isn't a fiscal story, it's an inflation one, and the BoJ is about to admit it. We lay out why a September pivot sends USD/JPY toward 99, and why global risk assets won't pay the price.

An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
