Monetary Policy

Long-dated bond yields rose another 48 bps since our last missive, quite a move in just a month. And yet, equities have remained resilient. This suggests that the move in bond yields is due to sanguine economic forces, not fiscal profligacy or inflation fears. In addition, the war in Iran is subsiding, partly because the Fed itself has conspired against it. Will President Trump restart the conflict regardless? Perhaps, however, the constraints are mounting against the White House foreign policy. We remain bullish on equities and reaffirm our view that investors with a long-term horizon should be nibbling at the current level of yields.
To make sure that our bearish clients are happy, we pivot to the risk of higher tax rates in the US. Specifically, we try to answer the question of when markets price higher tax rates.

Rising rates don’t halt bull markets but real yields exceeding the economy’s potential long-run growth rate could. That relative level could lead to a stock-bond collision if it persisted long enough to slow the economy.


Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.

Policy rates are poised to rise across the developed world as central banks are no longer willing to wait out the Iran-US standoff before taking action to combat the inflationary effects of higher oil prices. Outside of Japan, however, we do not think central banks will hike as much as markets expect.
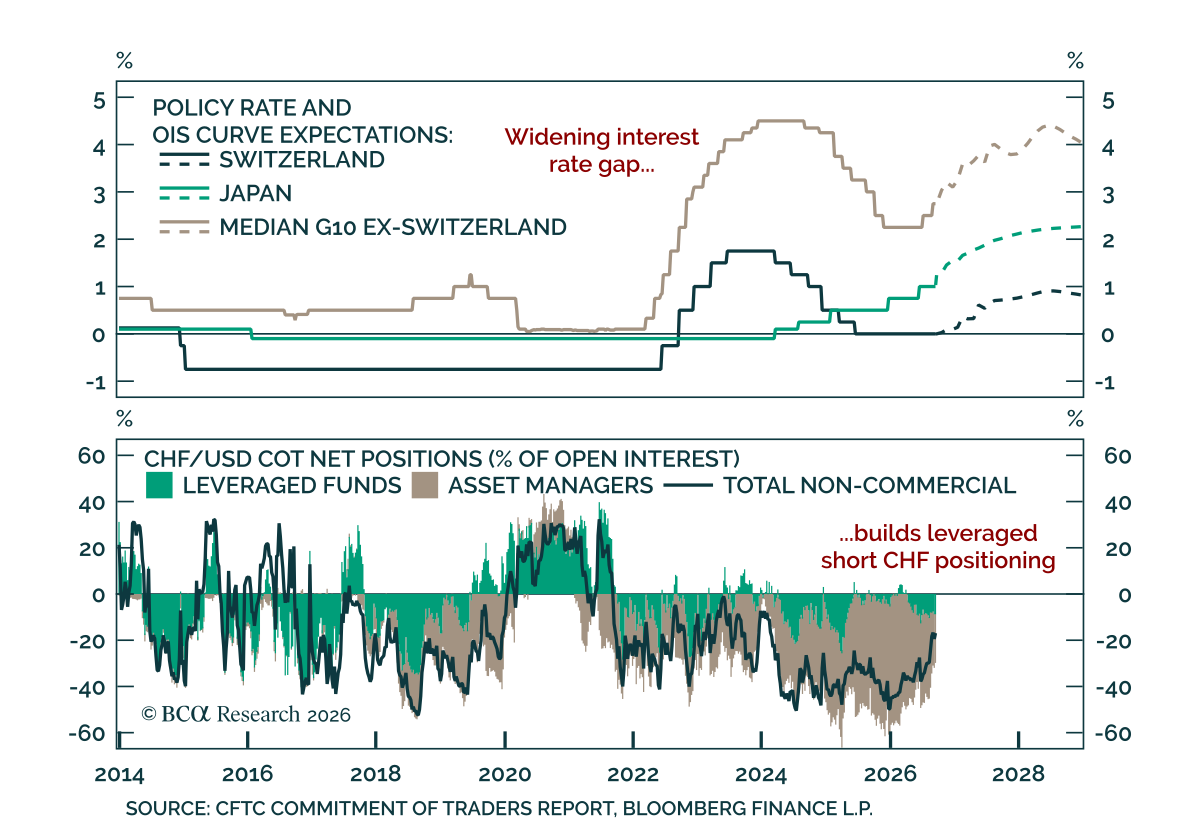


The Fed’s first hike is unlikely to be an equity-market cliff. Recent multiple compression has absorbed some of the rate shock, while bond risk premia, rate volatility, and inflation expectations remain contained. Stocks have typically climbed through hiking cycles, but we favor moving up in quality through our long/short Quality Capex Basket.
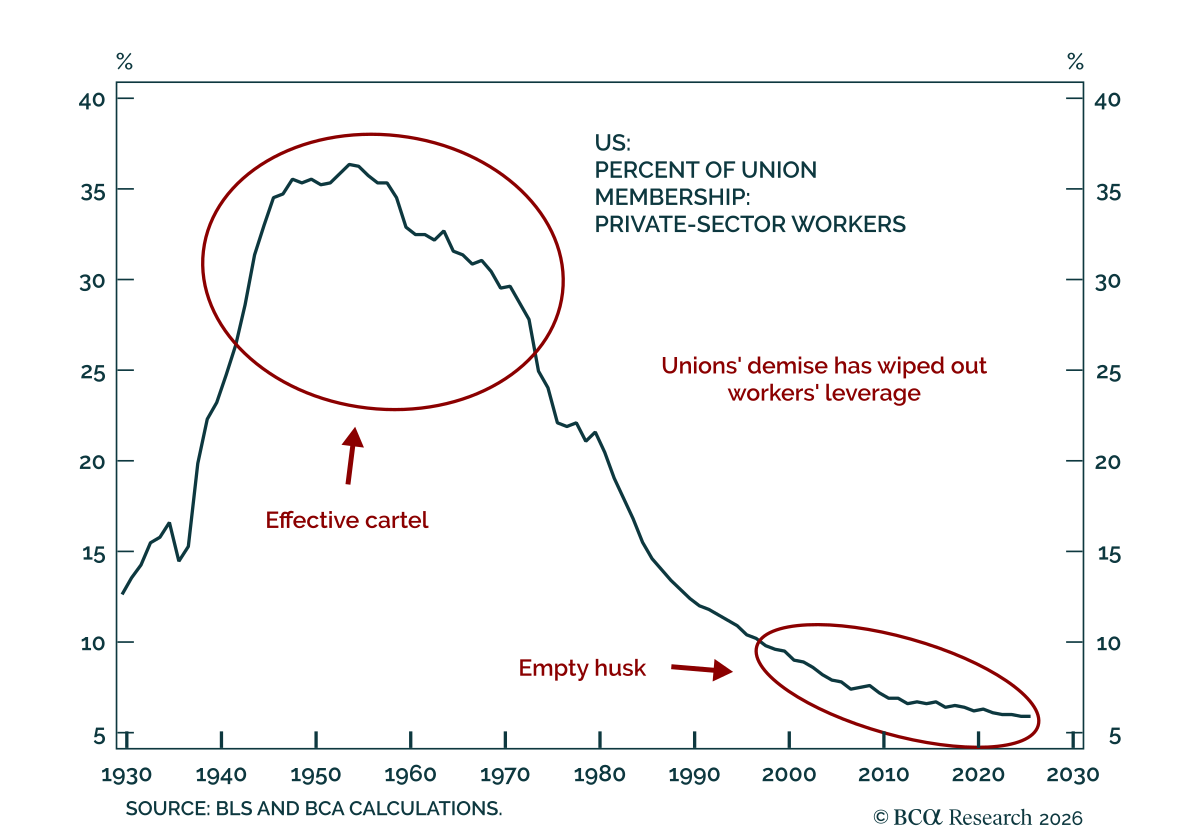

Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.